Published on
March 31, 2026

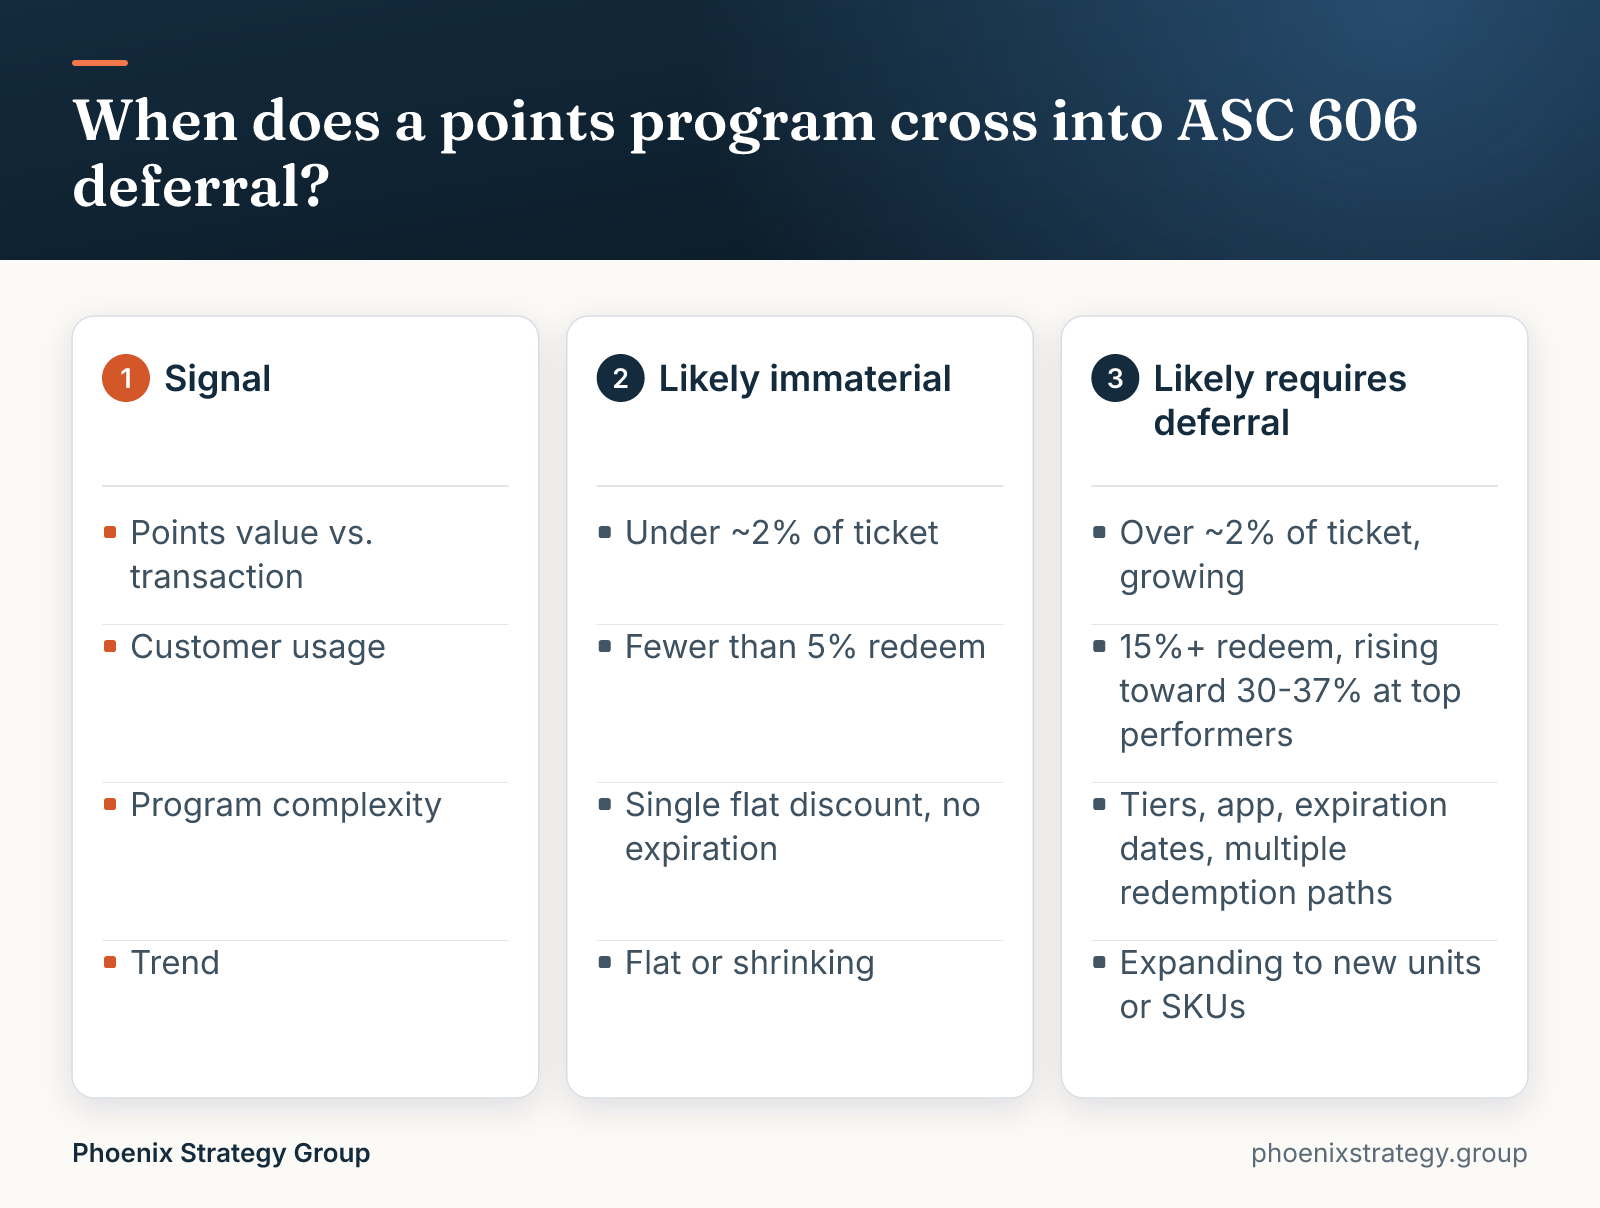
If points are worth less than roughly 2% of the transaction and fewer than 5% of your customers actually use them, you can likely treat the program as immaterial and skip the deferred revenue mechanics, documenting that judgment in a short materiality memo. If either number is higher, or you don't actually know the numbers, you need to build the liability. About two-thirds of restaurants now run some kind of loyalty program, and at quick-service chains it's closer to 71%, so this isn't a niche question anymore [1].
The SEC has been clear that no single percentage threshold is a rule of accounting law by itself, but a 5% misstatement is a commonly cited line for materiality in the absence of aggravating facts [2]. That's useful as a starting point, not a legal shield. A 10,000-point program handing out $0.50 discounts at a single taco stand is genuinely immaterial. A multi-unit group with an app, tiers, and a redemption rate north of 30% of transactions is not [3].
Here's the test I'd actually run: pull last year's point issuance, multiply by your average cost per point, and divide by total revenue. If that number is under 2% and shrinking, write the memo and move on. If it's growing, or your loyalty platform just launched a new tier structure, treat the program as material going forward even if last year's number was small, because the trend is what an auditor will ask about next year.
You split every sale into two pieces: the food and drink delivered today, and the material right to future food and drink, using the standalone selling price of each. The piece allocated to points gets booked as deferred revenue, not sales, until the customer redeems or the points expire [4].
Picture a $14M revenue restaurant group running six locations and an app-based points program: 1 point per dollar spent, 100 points redeemable for a $10 item. In a given month, customers spend $1.1M and earn 1.1M points. Based on the group's own redemption history, each point's standalone selling price works out to about $0.088 after adjusting for an estimated 20% breakage rate. That puts roughly $96,800 of the month's $1.1M in sales into deferred revenue, with the rest ($1,003,200) recognized as food and beverage revenue immediately.
This mirrors the mechanics in Deloitte's standard guidance: if a company determines $80 belongs to the product sold and $20 to the loyalty points on a $100 transaction, that $20 sits as a liability until redeemed, and any amount never redeemed gets released as breakage revenue in proportion to how customers are actually exercising their points [5]. The dollar-for-dollar scale changes with a six-unit group instead of a single sandwich, but the formula doesn't.
The old approach many restaurants used before ASC 606, booking the full sale as revenue and only expensing the cost of the free item at redemption, is no longer defensible for any program material enough to matter, and auditors reject it outright for material programs [6].
You estimate breakage from your own historical redemption curve, not an industry average, by grouping points into cohorts by the month they were earned and tracking what percentage of each cohort eventually gets redeemed. When actual redemption diverges from your original estimate, you true it up with a catch-up adjustment that flows through current-period revenue, not a restatement.
Take every cohort of points issued in a given month and track redemption over the following 12-18 months. Most restaurant programs show redemption slowing sharply after 90-120 days, with a long tail of stragglers who redeem just before expiration and then a group who never do. Plot cumulative redemption by month since issuance for several cohorts and you'll see the curve flatten out, that flat asymptote is roughly your breakage rate. You need at least 12 months of clean issuance and redemption data before you trust this; before that, use a conservative rate and say so in your documentation.
Say you originally estimated 25% breakage on a cohort of 500,000 points issued in January, deferring revenue as if 375,000 points would eventually redeem. By September, redemption data shows actual breakage trending closer to 35%, meaning fewer points are being redeemed than you planned for. You'd release an additional 10% of the original cohort, 50,000 points' worth of deferred revenue (at $0.088 per point, about $4,400), as breakage revenue in the current period as a cumulative catch-up adjustment, not spread retroactively across prior months.
Every month, you reconcile points issued and redeemed between your POS/loyalty platform and the general ledger, then roll the liability forward: beginning balance, plus new points issued (deferred), minus points redeemed (recognized as revenue), minus breakage released, equals ending balance. This is the single schedule an auditor will ask for first.
| Month | Beginning Liability | Points Issued (Deferred) | Points Redeemed (Recognized) | Breakage Recognized | Ending Liability |
|---|---|---|---|---|---|
| January | $210,000 | $96,800 | $(71,500) | $(9,200) | $226,100 |
| February | $226,100 | $88,400 | $(68,900) | $(8,700) | $236,900 |
| March | $236,900 | $101,200 | $(74,300) | $(9,900) | $253,900 |
The matching journal entries are simple once you've done the allocation math. At sale: debit cash, credit food revenue for the non-point portion, credit loyalty liability for the point portion. At redemption: debit loyalty liability, credit food revenue (or inventory/COGS, depending on how you've built your chart of accounts). At breakage release: debit loyalty liability, credit breakage revenue. Run this monthly even if your reconciliation is quarterly, because the rollforward only works if nothing slips a period.
Where the data actually comes from matters. Punchh, Paytronix, Olo, and Fivestars all export point issuance and redemption, but they don't structure that data the same way, and that affects how much manual cleanup your reconciliation needs.
| Platform | Data granularity | Redemption detail | Best fit |
|---|---|---|---|
| Punchh | Transaction-level, tied to POS | Strong redemption and expiration tracking | Multi-brand enterprise groups |
| Paytronix | Transaction-level with tier history | Good cohort and tier reporting | Full-service groups with tiered programs |
| Olo | Order-level, integrated with online ordering | Redemption tied to digital orders primarily | Groups leaning heavily on app/online ordering |
| Fivestars | Visit-based, less granular on dollar value | Simpler redemption export, less tier detail | Single-concept or smaller multi-unit operators |
Deferred loyalty revenue sits on your balance sheet as a liability, but the cash from that sale already hit your bank account, so your GAAP revenue and your actual spendable cash diverge every month the program grows. A CFO who forecasts cash off the P&L instead of off collections will overspend against revenue that isn't real yet.
Build your cash forecast off cash collected, not recognized revenue. If $96,800 of this month's $1.1M in sales is deferred as loyalty liability, that's still real cash sitting in your bank account, you just can't count it as earned revenue for growth planning purposes. The risk isn't that you lack the cash, it's that a founder looks at a GAAP income statement, sees strong revenue, and green-lights a new lease or hire against a number that includes revenue the business hasn't actually earned yet.
When you're in a credit renewal or building a CIM, show the loyalty liability rollforward as a standalone schedule, not buried in a footnote. Lenders get nervous about line items they don't understand, and a liability that moves unpredictably invites questions about your controls. Walking them through issuance, redemption, and breakage with a clean monthly rollforward turns a scary-looking number into evidence you have a disciplined process. Most covenant EBITDA calculations don't adjust for breakage revenue, so make sure your lender understands which part of revenue is cash-backed and which part is a timing allocation.
GAAP lets you defer loyalty and gift card revenue for as long as your redemption data supports, sometimes years. The IRS doesn't give you that long.
| Item | GAAP (book) treatment | Tax treatment | Practical gap |
|---|---|---|---|
| Deferred revenue recognition | Deferred until redemption/expiration, can span years [4] | Deferral election generally limited to one year beyond receipt [7] | Tax income often recognized well before GAAP revenue |
| Advance payments for gift cards | Full deferral supported by redemption data | Maximum one-year deferral; must include remainder in income year two even if GAAP still defers it [8] | Can create a tax bill on revenue not yet shown as earned on the books |
| Unclaimed property exposure | Not a GAAP revenue issue directly | States can claim unredeemed balances, with look-back periods of 10-15 years across roughly 54 jurisdictions [8] | Separate liability risk outside the ASC 606 analysis entirely |

Multi-tier and punch-card hybrids need the same material-right analysis as simple point-per-dollar programs, but the standalone selling price allocation gets done per tier or per reward type, not as one blended rate, because the value a customer actually gets varies by level or by card type.
A punch card (buy 9 coffees, get the 10th free) is actually simpler to value than a points app: you know exactly what the reward is worth and how many purchases it takes to earn it, so the SSP is close to the face value of the free item divided across the required purchases, adjusted for the share of customers who never finish the card. A tiered points program (bronze/silver/gold, each with different earn rates and perks) needs a separate breakage and SSP estimate per tier, because a gold member redeems far more reliably than a bronze member who signed up once and never came back.
The practical move for a growth-stage group: track issuance and redemption separately by tier in your subledger from day one. Retrofitting tier-level tracking after two years of blended data is painful and usually means falling back on conservative, higher-than-actual breakage assumptions until you've rebuilt the history.
An audit-ready process has a documented SSP methodology, a breakage rate that's been updated at least annually against actual redemption data, and a liability account that ties out to the loyalty platform every month, with a clear paper trail an auditor can follow from POS transaction to GL entry.
Revisit your breakage estimate whenever something changes the redemption pattern: a new promotion, a change to expiration policy, a new tier launch, or an acquisition that brings in a different customer base with different redemption habits. Waiting for the annual audit to notice the drift is how a small estimate error becomes a restated financial statement.
If you'd rather not build this by hand, Dear CFO builds it from your QuickBooks, tying the loyalty platform export straight into the rollforward so the monthly close doesn't depend on a spreadsheet someone built two finance hires ago.
Loyalty point accounting isn't hard once you've built the rollforward once: issue, redeem, release breakage, update your estimate, repeat. The part that actually matters for a $2M-$50M restaurant group isn't the formula, it's the discipline of revisiting your breakage rate against real data, keeping cash forecasting separate from GAAP revenue, and being able to hand an auditor or a lender a clean monthly schedule instead of a year-end guess. Get the process right once and it runs itself every month after.
If points give a material right to a discount customers wouldn't otherwise get, a portion of the sale is deferred as a liability on the balance sheet and recognized as revenue only when the points are redeemed or expire, under ASC 606 [4][6]. If the program is small enough to be immaterial, you can skip the deferral and recognize the full sale as revenue.
Breakage is the portion of gift card or point value you expect customers will never redeem; you recognize that amount as revenue in proportion to how customers are actually redeeming the rest, or all at once if redemption of the remainder becomes remote [5]. For example, on a $40 gift certificate where $10 is never redeemed, that $10 gets released as breakage revenue rather than sitting as a liability forever.
Build a historical redemption curve from cohorts of points or gift cards issued in the same period, use the flattened tail of that curve as your breakage estimate, and release that estimated unredeemed value into revenue proportionally as actual redemptions occur. Revisit the estimate at least quarterly and book a catch-up adjustment to current-period revenue whenever actual redemption data diverges meaningfully from your original estimate.
Breakage revenue is the portion of a gift card, loyalty point, or similar prepaid liability that a company recognizes as earned because it no longer expects the customer to redeem it. It moves a previously deferred liability onto the income statement once the likelihood of redemption drops to remote, or gradually as actual redemption patterns confirm the unredeemed portion [5].

About the author
Partner, Phoenix Strategy Group
Ethan Lu is a Partner at Phoenix Strategy Group, where he works as a fractional CFO helping founder-led companies maximize their exit value. He currently oversees more than $200M in client enterprise value and has been part of multiple eight-figure exits. Before PSG he was an asset manager and investor for a San Diego family office, where he sat on the investment committee for more than $1B in assets. A data scientist by training, he holds a B.S. in Mathematics with a minor in Accounting from UC San Diego.
Talk to a PSG CFO about your numbers
Phoenix Strategy Group does CFO work for growth-stage companies.
Schedule a call